
Get pre-approved by a local lender
Answer a few quick questions and we’ll connect you with a local lender to discuss your financing options — no pressure, no obligation.

Meet your Trusted OriginPoint Lender
Vetted professionals with a proven track record of fast, smooth closings.
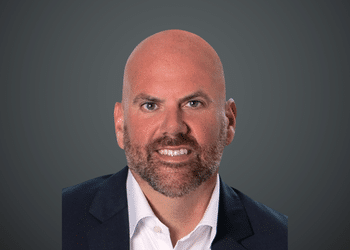
Michael Gambatese
OriginPoint – NMLS# 222968
- Residential Mortgage
- Refinance
- FHA financing
- Certified Mortgage Planning

Michael Murray
OriginPoint – NMLS# 223808
- Mortgage Lending
- Conventional Loans
- Refinance
- Residential
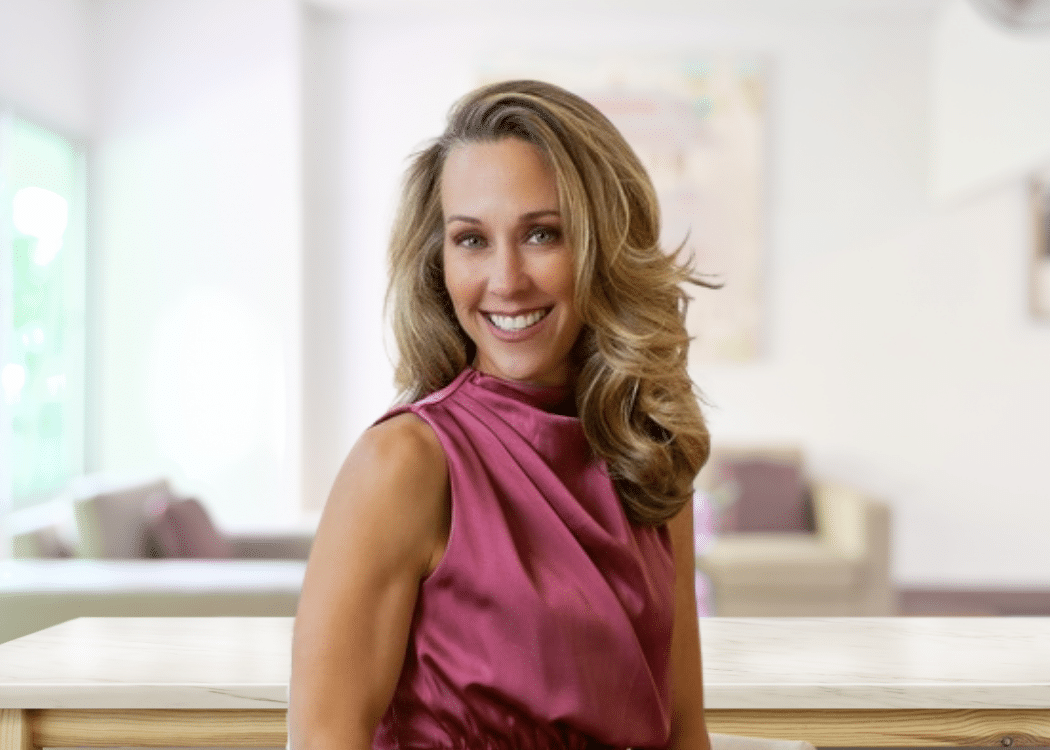
Erin Stojakovic
OriginPoint – NMLS# 224531
- Certified Divorce Lending
- Refinance
- Residential
- First Time Buyers
Your path to homeownership
From initial pre-approval to moving day, we make it simple.
Get Pre-Approved
Connect with a local expert to start the pre-approval process.
Make An Offer
Your pre-approval letter lets sellers know you are serious.
Close & Move In
Clear loan conditions, sign docs, and get the keys.
Home loan options
Compare top loan options, rates, and terms.
30-Year Fixed
- Most popular
- XX% down options
- Lowest monthly payment
- Fixed interest rate
- Long-term stability
30-Year FHA
- Lower credit profiles
- XX% down options
- Flexible credit rules
- FHA-backed program
- Great for first-time buyers
30-Year VA
- Eligible military
- 0% down payment
- No PMI required
- Lower interest rates
- For veterans & service members
20-Year Fixed
- Save on interest
- XX% down options
- Lower total interest
- Faster payoff than 30-year
- Fixed monthly payment
15-Year Fixed
- Faster payoff
- XX% down options
- Least interest paid
- Build equity faster
- Paid off in 15 years
Mortgage rates aren’t one size fits all. Speak with a trusted local lender to
Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply.
OriginPoint is a private corporation organized under the laws of the State of Delaware. It has no affiliation with the US Department of Housing and Urban Development, the US Department of Veterans Affairs, the Nevada Department of Veterans Services, the US Department of Agriculture, or any other government agency. No compensation can be received for advising or assisting another person with a matter relating to veterans’ benefits except as authorized under Title 38 of the United States Code.
Compass, its affiliated brokerages and OriginPoint, LLC share common ownership and because of this relationship, the Compass affiliated brokerage may receive financial and other benefits. You are not required to use OriginPoint, LLC as a condition of purchase or sale of any real estate.
Operating in the state of California as OriginPoint Mortgage LLC in lieu of the legal name OriginPoint LLC.
OriginPoint LLC; NMLS #2185899; OriginPoint.com; 1800 W Larchmont Ave Suite 305, Chicago, IL 60613; 855-997-6468. For licensing information visit nmlsconsumeraccess.org. Equal Housing Lender. Conditions may apply. AZ: OriginPoint LLC – 15333 North Pima Road, Suite 305, Office 337, Scottsdale, AZ 85260, Mortgage Banker License #1038328• CA: Licensed by the Department of Financial Protection and Innovation (DFPI) under the California Residential Mortgage Lending Act RMLA #41DBO-150076 • CO: Regulated by the Division of Real Estate • GA: Residential Mortgage Licensee #2185899 • MA: OriginPoint LLC – Mortgage Lender & Mortgage Broker License MC2185899 • ME: Maine Supervised Lender License #2185899 • NH: OriginPoint LLC, licensed by the New Hampshire Banking Department NJ: Licensed by the N.J. Department of Banking and Insurance • OR: Licensed and Regulated by the Department of Consumer and Business Services• PA: Licensed by the Pennsylvania Department of Banking and Securities • RI: Rhode Island Licensed Lender and Loan Broker • WA: Consumer Loan Company License CL-366423
Let’s unlock your purchasing power.
Connect with a lender to find out exactly what you can afford.
Financing Resources
Guides and strategies to help you buy smarter and save money.
Looking for additional resources? Visit our Learning Center
Your questions, answered.
Straight answers to the most common home loan questions.
How long does pre-approval take?
Pre-approval timelines vary by lender, but many buyers can receive a basic pre-approval within 24 to 72 hours after submitting an application and required documents. The exact timing depends on your financial situation and how quickly documents are provided. A trusted lender can walk you through the process and set clear expectations.
Do I have to choose a loan today?
No. Exploring loan options early is part of being an informed buyer, not a commitment. Most buyers review different loan types, compare lenders, and ask questions before making a final decision. Taking time to understand your options helps you choose a loan that fits your long-term goals.
What is a conventional loan?
A conventional loan is a mortgage that is not insured by a government program (like FHA or VA). These loans are commonly used and typically require stronger credit and a higher down payment compared to some government-backed options. Many buyers choose conventional loans for their flexibility and competitive rates.
What is an FHA loan?
An FHA loan is a mortgage backed by the Federal Housing Administration. These loans are designed to make homeownership more accessible and often allow for lower down payments and more flexible credit requirements. They are especially popular with first-time homebuyers.
What is a VA loan?
A VA loan is a mortgage option available to eligible veterans, active-duty service members, and certain military families. These loans are backed by the Department of Veterans Affairs and may offer benefits such as no down payment and competitive interest rates for qualified borrowers.
What does debt-to-income ratio (DTI) mean?
Debt-to-income ratio (DTI) is a comparison of your monthly debt payments to your gross monthly income. Lenders use this number to help evaluate how comfortably you may be able to manage a mortgage payment alongside your other financial obligations.
What is loan-to-value ratio (LTV)?
Loan-to-value ratio (LTV) compares the amount of the loan to the value of the property. For example, if you purchase a home for $300,000 and borrow $270,000, your LTV would be 90%. LTV can influence loan options, rates, and down payment requirements.
What is a down payment in real estate?
A down payment is the portion of the purchase price you pay upfront when buying a home. The amount can vary depending on the type of loan, your financial situation, and lender requirements. Some loan programs allow for lower down payments, while others may require more.
Start Your Next Move With Confidence
Explore listings, connect with a local expert, and take the next step today.
No pressure. Honest advice. Clear next steps.